Math
Kalman filter
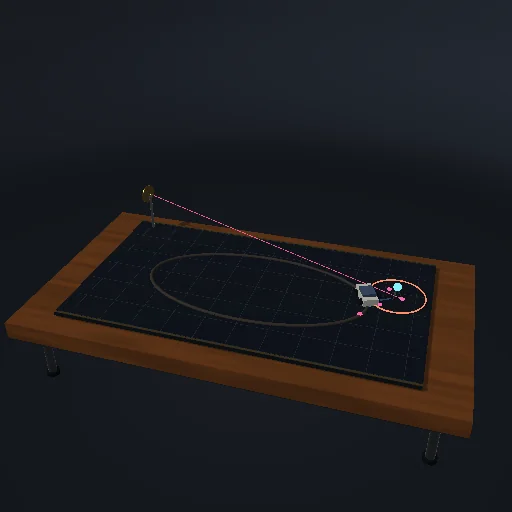
Track a moving target with a two-dimensional Kalman filter. Tune process and measurement noise, compare raw observations with the estimate, and inspect the covariance ellipse.
Try this
White is the true moving target, pink the noisy position measurements, blue the estimate. The orange ellipse uses two standard deviations along covariance eigenvectors.
Equations used in the module
Equations
x− = F x; P− = F P Fᵀ + Q
K = P−Hᵀ(HP−Hᵀ + R)⁻¹
x+ = x− + K(z − Hx−)
P+ = (I−KH)P−(I−KH)ᵀ + KRKᵀ